
Updated October 2026
Imagine returning to your parked vehicle and discovering that another driver has struck it.
You might assume that because your vehicle was not moving, you cannot be responsible for the accident.
In most situations, that assumption is correct.
However, Ontario's automobile insurance rules contain an important exception involving vehicles that are illegally parked, stopped or standing outside a city, town or village.
The location of the accident and the circumstances surrounding it can make a significant difference in how fault is determined.
There are also special rules for parking lots, vehicles backing out of parking spaces and accidents involving open vehicle doors.
At L.D. Dermody Insurance Brokers, we believe that understanding how Ontario insurers determine fault can help drivers avoid surprises when making an automobile insurance claim.
Here is what Ontario drivers should know.
1. How Is Fault Determined After an Automobile Accident in Ontario?
When an automobile accident occurs, insurance companies must determine the degree of fault assigned to their insured drivers.
In Ontario, this assessment is generally made using the province's Fault Determination Rules, established under Regulation 668 of the Insurance Act.
These rules describe common accident situations and specify how fault is to be assigned.
Depending on the circumstances, a driver may be assessed as:
-
0% at fault.
-
25% at fault.
-
50% at fault.
-
75% at fault.
-
100% at fault.
The percentage depends on the applicable rule.
The Fault Determination Rules are designed to provide a consistent approach to assessing automobile accidents for insurance purposes.
This means that an insurance company's assessment may differ from what a driver personally considers fair or reasonable.
It is also important to understand that insurance fault is not necessarily determined by whether police issue a traffic ticket.
2. Who Is at Fault When a Legally Parked Vehicle Is Hit?
Section 17(1) of Ontario's Fault Determination Rules addresses this situation directly.
Where one automobile is parked and is struck by another automobile, the regulation generally assigns:
-
0% fault to the driver of the parked vehicle.
-
100% fault to the driver of the vehicle that strikes it.
Example: A Parked Car Is Hit on a Residential Street
You park your vehicle legally along a residential street.
While driving past, another motorist misjudges the distance and strikes the side of your vehicle.
Under section 17(1), the parked vehicle is generally assessed as 0% at fault, while the moving vehicle is assessed as 100% at fault.
The same general principle applies when a legally parked vehicle is struck in a parking lot.
However, determining fault is only one part of an insurance claim.
The coverage available for repairs depends on the policy and other circumstances, including whether the responsible driver can be identified.
3. What if Your Vehicle Was Parked Illegally?
This is where Ontario's rules become particularly interesting.
Some drivers assume that parking illegally automatically makes them responsible for any accident involving their vehicle.
That is not what the regulation says.
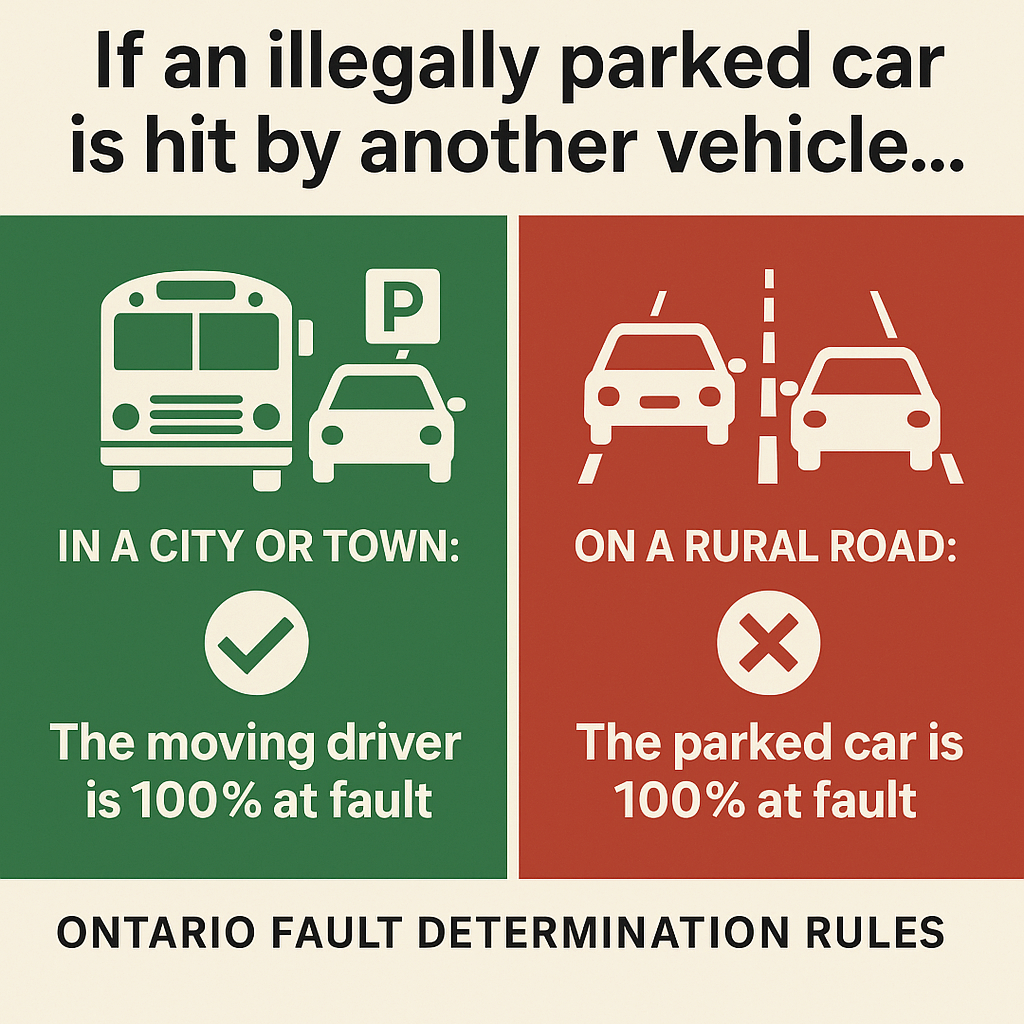
Section 17(2) creates a specific exception.
If a vehicle is illegally parked, stopped or standing outside a city, town or village when another vehicle strikes it, the rule assigns:
-
100% fault to the driver of the illegally parked, stopped or standing vehicle.
-
0% fault to the driver of the vehicle that strikes it.
This is a significant exception to the general rule protecting parked vehicles.
The location of the accident is therefore extremely important.
Example: A Vehicle Parked Illegally on a Rural Road
A driver leaves a vehicle illegally parked along a rural road outside a city, town or village.
Another vehicle subsequently strikes it.
If section 17(2) applies, the driver of the illegally parked vehicle is assessed as 100% at fault for insurance purposes.
This may surprise the vehicle owner, who might argue that their vehicle was stationary and the other driver should have avoided it.
Nevertheless, the regulation specifically addresses this situation.
4. What if Your Vehicle Is Illegally Parked in a City or Town?
The exception in section 17(2) is specifically limited to incidents occurring outside a city, town or village.
It does not establish the same automatic 100% fault assessment for an illegally parked vehicle within a city, town or village.
Example: An Illegally Parked Vehicle on a City Street
A driver parks in a prohibited parking area on a city street.
Another motorist strikes the parked vehicle.
The fact that the vehicle was illegally parked does not, by itself, bring the accident within section 17(2).
Under the general parked-vehicle rule in section 17(1), the parked vehicle would ordinarily be assessed as 0% at fault and the moving vehicle as 100% at fault, assuming no other applicable provision changes the assessment.
The illegally parked driver may still receive a parking ticket or face other consequences for the parking violation.
However, a parking violation and an insurance fault assessment are separate matters.
The important distinction is that illegally parking a vehicle does not automatically make its owner at fault for every collision involving that vehicle.
5. Why Does the Location Matter?
Ontario's Fault Determination Rules contain specific provisions for different accident circumstances.
Section 17(2) expressly refers to vehicles illegally parked, stopped or standing outside a city, town or village.
This wording means that the exception has a geographical limitation.
When reviewing an accident involving an illegally parked vehicle, the insurer must consider where the collision occurred.
A rural roadside collision may be assessed differently from a similar collision on a city street.
Drivers should not assume that every location with a rural appearance necessarily falls outside a city, town or village.
Municipal boundaries and the precise location of the incident may need to be established.
If you disagree with an insurer's assessment, ask which section of the Fault Determination Rules was applied and how the insurer determined that it matched the circumstances.
6. What Happens if a Vehicle Is Parked on the Shoulder of a Road?
Not every vehicle stopped on a roadside shoulder is illegally parked.
A driver may stop because of a mechanical breakdown, emergency or another circumstance.
Whether stopping or parking is permitted depends on the applicable traffic laws, signs and conditions.
For insurance purposes, the distinction between a vehicle that is legally parked and one that is illegally parked, stopped or standing can become important.
The insurer must consider the facts and determine which rule applies.
If you must stop because of an emergency, take reasonable steps to protect yourself and other road users.
Where possible:
-
Move the vehicle to a safe location.
-
Activate hazard warning lights.
-
Avoid stopping in a travel lane.
-
Follow applicable roadside safety requirements.
-
Seek roadside assistance when necessary.
If your vehicle is struck, provide the insurer with a clear explanation of why it was stopped and its exact location.
7. Are Parking Lot Accidents Always Considered 50/50 Fault?
No.
This is one of the most common misconceptions about automobile insurance.
Some drivers believe that whenever two vehicles collide in a parking lot, each driver is automatically assessed as 50% at fault.
Ontario's Fault Determination Rules do not establish such a blanket rule.
Section 16 contains specific rules for parking lot accidents.
The fault assessment depends on what the vehicles were doing and where the collision occurred.
For example, the rules distinguish between vehicles travelling along main parking lot routes, vehicles leaving feeder lanes and vehicles leaving parking spaces.
A parking lot accident can result in a 0%, 50% or 100% fault assessment, depending on the applicable circumstances.
8. What if Someone Hits Your Parked Vehicle in a Parking Lot?
If your vehicle is properly parked in a parking space and another driver strikes it, section 17(1) generally applies.
The parked vehicle is assessed as 0% at fault and the moving vehicle as 100% at fault.
Example: A Shopping Centre Parking Lot
You park your vehicle in a designated parking space at a shopping centre.
While you are inside, another driver turns too sharply and strikes your vehicle.
Assuming the circumstances are established, your parked vehicle would ordinarily be assessed as 0% at fault.
However, if the other driver leaves without identifying themselves, there may be additional issues concerning the coverage available to repair your vehicle.
Being assessed as not at fault does not necessarily mean that every repair expense will automatically be paid.
9. Who Is at Fault When Backing Out of a Parking Space?
Section 16(4) addresses vehicles leaving parking spaces and failing to yield to traffic in parking lot lanes.
Where a vehicle leaves a parking space and fails to yield to another vehicle travelling on a feeder lane or thoroughfare, the driver leaving the parking space is assessed as 100% at fault.
Example: Backing Into a Passing Vehicle
You are backing out of a parking space at a grocery store.
Another vehicle is travelling along the parking lot lane.
You fail to yield and your vehicle strikes the passing vehicle.
Under section 16(4), you would generally be assessed as 100% at fault.
There is also a broader provision in section 19 concerning vehicles that are backing up.
This is why drivers should be particularly careful when reversing.
Before backing out:
-
Check mirrors and blind spots.
-
Look for pedestrians and cyclists.
-
Watch for approaching vehicles.
-
Reverse slowly.
-
Stop if visibility is obstructed.
Backup cameras are helpful, but they do not replace the need to check your surroundings.
10. What if Two Vehicles Back Into Each Other?
Consider two drivers parked opposite each other in a parking lot.
Both begin backing out at approximately the same time and their vehicles collide.
Section 19 addresses accidents involving a vehicle that is backing up.
However, when more than one fault rule applies, the regulation also contains provisions for resolving the applicable assessments.
In some circumstances, two vehicles backing into one another may each be assessed as 50% at fault.
The actual determination depends on the established facts and the interaction of the relevant rules.
For this reason, it is not appropriate to assume that every backing accident automatically results in one driver being 100% responsible.
Photographs, witness statements and video recordings can be particularly useful when determining what happened.
11. What Happens if Someone Opens a Car Door Into Traffic?
Opening a vehicle door into the path of another vehicle can cause serious damage or injury.
This is especially concerning when cyclists are passing parked vehicles.
Section 19(c) addresses collisions occurring when a driver or passenger opens a vehicle door or leaves it open.
Under this provision, the driver of the automobile with the open door is assessed as 100% at fault, while the driver of the other automobile is assessed as 0% at fault.
Example: A Door Is Opened Into a Passing Car
A passenger opens the door of a parked vehicle just as another automobile is passing.
The passing vehicle strikes the open door.
Under section 19(c), the driver of the vehicle with the open door would generally be assessed as 100% at fault.
This is an important reminder that drivers can face insurance consequences arising from the actions of their passengers.
Before opening a door, check carefully for approaching vehicles, cyclists and pedestrians.
12. What if Someone Hits Your Parked Vehicle and Leaves?
Discovering damage to your parked vehicle without knowing who caused it can be frustrating.
Unfortunately, hit-and-run incidents create additional insurance complications.
The first step is to document the damage and gather as much information as possible.
You should:
-
Take photographs of the damage and surrounding area.
-
Record where and when the vehicle was parked.
-
Look for witnesses.
-
Ask nearby businesses whether security footage may be available.
-
Follow applicable police or collision reporting requirements.
-
Contact your insurance broker or insurer promptly.
The availability of insurance coverage depends on the circumstances and the coverage purchased.
If the Other Driver Is Identified
Where the responsible driver and vehicle are identified and the conditions for applicable coverage are met, the claim may be handled differently from one involving an unidentified vehicle.
If the Other Driver Is Never Identified
Damage caused by an unidentified driver may need to be considered under your Collision or All Perils coverage, if purchased.
A deductible may apply.
Ontario's Uninsured Automobile coverage has specific conditions and should not be assumed to cover ordinary vehicle damage caused by an unidentified hit-and-run driver.
Your broker can help explain which section of your policy may respond.
13. Does a Not-at-Fault Accident Mean You Never Pay a Deductible?
Not necessarily.
Fault determination and the application of an insurance deductible are related but separate questions.
Ontario automobile policies can include several types of physical damage coverage.
Direct Compensation – Property Damage (DCPD)
DCPD may provide coverage for damage to your vehicle when another driver is at fault, provided the statutory and policy conditions are met.
Ontario drivers may now elect not to claim DCPD coverage, so it is important to verify whether this protection is available under your policy.
Where DCPD applies, a deductible may or may not apply depending on the policy.
Collision Coverage
Collision coverage generally addresses certain damage arising from a collision or upset, subject to policy terms and exclusions.
It commonly carries a deductible.
All Perils Coverage
All Perils combines specified types of physical damage protection and may respond to certain losses subject to the policy's terms.
The deductible and coverage available depend on the applicable policy provisions.
A vehicle owner can therefore be assessed as 0% at fault and still have an uninsured expense or deductible, depending on the circumstances.
14. Does a Not-at-Fault Accident Increase Your Insurance Premium?
An accident assessed as 0% at fault is generally treated differently for insurance rating purposes from an accident assessed as partially or fully at fault.
However, the effect on premiums and eligibility depends on the insurer's approved rating and underwriting rules.
Drivers should not assume that every claim will have identical consequences.
For example, an insurer may distinguish between:
-
A not-at-fault accident involving an identified driver.
-
A hit-and-run loss involving an unidentified vehicle.
-
An accident assessed as 50% at fault.
-
An accident assessed as 100% at fault.
The type of claim and coverage used may also matter.
If you have questions about how a claim could affect your renewal, ask your broker to explain the insurer's treatment of the accident.
15. Does Receiving a Traffic Ticket Automatically Make You at Fault?
No.
Insurance fault and traffic offences are determined under different systems.
A police officer may issue a ticket for a violation of the Highway Traffic Act or another applicable law.
An insurance company generally determines fault under Ontario's Fault Determination Rules.
For example, a driver might receive a parking ticket for stopping in a prohibited location.
That ticket does not automatically establish the driver's percentage of fault for an accident.
Likewise, a driver may be assessed as 100% at fault for an accident even if police do not lay a charge.
There are specific provisions in the Fault Determination Rules for certain driving offences, including circumstances involving impairment, particular serious offences and specified speeding charges.
Those provisions can affect how fault is assessed.
However, the mere existence of a ticket does not automatically override every other fault rule.
16. Do Weather and Road Conditions Affect Fault?
Many drivers believe that poor weather should reduce their responsibility for an accident.
For example, someone might explain that they slid into a parked vehicle because the road was icy.
However, section 3 of Ontario's Fault Determination Rules generally requires fault to be determined without reference to circumstances such as:
-
Weather conditions.
-
Road conditions.
-
Visibility.
-
Actions of pedestrians.
This can surprise drivers.
Example: Sliding Into a Parked Vehicle
A driver loses control on an icy road and strikes a legally parked vehicle.
The driver may feel that the collision was unavoidable because of the road conditions.
Nevertheless, the parked-vehicle rule generally assigns 100% fault to the driver who struck the parked vehicle.
Drivers are expected to adjust their driving to the conditions.
The Fault Determination Rules are intended to produce consistent insurance assessments rather than individualized judgments about every contributing circumstance.
17. What if You Disagree With the Insurance Company's Fault Assessment?
Insurance companies can make mistakes, and disagreements can arise when the parties provide different accounts of an accident.
If you believe the assessment is incorrect, ask the insurer to explain how it reached its decision.
You should request:
-
The section of the Fault Determination Rules used.
-
The facts the insurer relied upon.
-
An explanation of why the rule applies.
-
Clarification of any disputed information.
Review the insurer's explanation carefully.
If important facts are incorrect or missing, provide supporting evidence.
This might include:
-
Photographs.
-
Dashcam footage.
-
Security camera recordings.
-
Witness statements.
-
Police reports.
-
A diagram showing vehicle positions and movements.
If the matter remains unresolved, ask about the insurer's internal complaint process and available escalation options.
Your insurance broker can help you understand the applicable rules and communicate your concerns to the insurer.
18. Why Is Accurate Information So Important After an Accident?
The Fault Determination Rules often depend on specific details about how the vehicles were positioned and moving.
For example, there can be a significant difference between a vehicle that was:
-
Legally parked.
-
Illegally parked.
-
Stopped temporarily in traffic.
-
Pulling away from a parking space.
-
Backing out of a parking space.
-
Entering a roadway.
-
Travelling along a parking lot thoroughfare.
Even small differences in the facts may result in a different fault assessment.
When reporting an accident, provide a clear and accurate description of what happened.
Avoid guessing about details you did not personally observe.
If you discover damage after returning to a parked vehicle, explain that you did not witness the collision.
If the other driver provides a different account, identify the specific points of disagreement and provide any supporting evidence available.
19. How Can You Reduce the Risk of Parking-Related Accidents?
Although accidents cannot always be prevented, there are practical steps drivers can take.
Choose legal parking locations. Avoid stopping where parking is prohibited or where your vehicle could obstruct traffic.
Consider visibility. Avoid parking in locations where approaching drivers may have difficulty seeing your vehicle.
Allow sufficient clearance. Leave room for other vehicles to manoeuvre.
Check before opening doors. Look for passing vehicles, cyclists and pedestrians.
Use extra care when reversing. Check your surroundings and move slowly.
Avoid obstructing driveways and intersections. These locations can create additional hazards.
Document accidents promptly. Photographs and witness information can help establish the circumstances of a collision.
Safe parking practices help protect your vehicle and other road users.
20. What Ontario Drivers Should Remember
Ontario's Fault Determination Rules can produce results that are not always obvious.
The most important points are:
-
A legally parked vehicle that is struck by another automobile is generally assessed as 0% at fault.
-
An illegally parked, stopped or standing vehicle outside a city, town or village may be assessed as 100% at fault under the specific exception in section 17(2).
-
Illegal parking within a city or town does not automatically result in the same fault assessment.
-
Parking lot accidents are not automatically assessed as 50/50.
-
Drivers leaving parking spaces or backing up can be assessed as 100% at fault.
-
Opening a vehicle door into another automobile's path can result in a 100% fault assessment.
-
A police ticket and an insurance fault determination are separate matters.
-
Being assessed as not at fault does not guarantee that every repair expense will be covered without a deductible.
The applicable rule and the facts of the accident determine the outcome.
Understanding Your Automobile Insurance Before a Claim
Most drivers do not think about Ontario's Fault Determination Rules until they are involved in an accident.
However, understanding how these rules work can help explain why an insurer reaches a particular decision.
It is equally important to understand the physical damage coverage provided by your automobile policy.
Collision coverage, DCPD coverage, deductibles and other policy provisions can affect how a claim is handled, even when you are not responsible for the accident.
At L.D. Dermody Insurance Brokers, we help Ontario drivers understand their automobile insurance coverage and the claims process.
If you have questions about your automobile insurance, coverage for damage to your vehicle or an insurer's fault assessment, contact L.D. Dermody Insurance Brokers.
We would be pleased to help you understand the coverage available under your policy.
This article provides general information about Ontario automobile insurance as of October 2026. Fault assessments are governed by the applicable Fault Determination Rules and the established circumstances of each accident. Insurance coverage, deductibles and rating consequences depend on policy terms, legislation and insurer rules. This article is not legal advice.

