
Updated October 2026
Starting and operating a small business involves considerable responsibility.
Whether you operate a retail store, provide professional services, work as a contractor or run a business from your home, there are risks that could result in substantial financial losses.
An unexpected fire, a customer injury, a lawsuit, stolen equipment or a cyberattack can disrupt operations and threaten the financial stability of a business.
Insurance can help protect against many of these risks, but choosing the right coverage is not always straightforward.
One of the most common questions we hear is:
1. Why Does Contractor Insurance Matter?
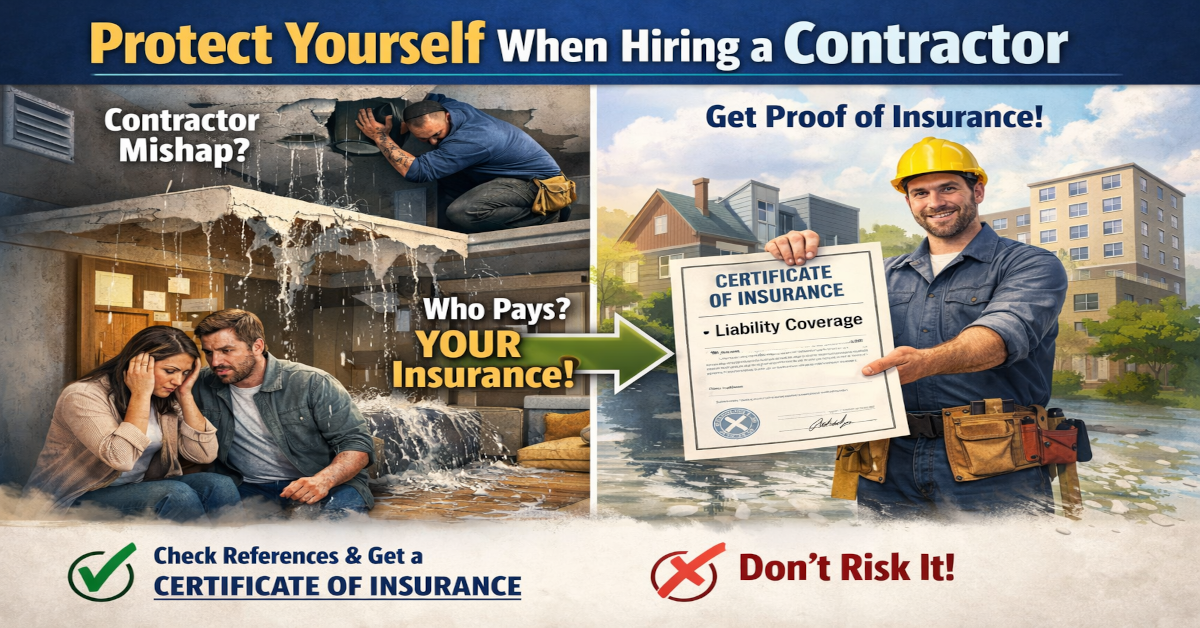
Even experienced and reputable contractors can make mistakes or be involved in accidents.
Consider these examples:
-
A roofing contractor accidentally damages part of your home while replacing shingles.
-
A plumber causes a water leak that damages finished walls and flooring.
-
A contractor's equipment damages a neighbouring property.
-
A visitor is injured because of an unsafe condition created during renovation work.
-
A fire occurs while a contractor is performing work involving heat-producing equipment.
Depending on the circumstances, the contractor could be held legally responsible for some or all of the resulting damage or injury.
If the contractor has appropriate liability insurance, that policy may respond to a covered claim.
If the contractor is uninsured, underinsured or performing work outside the scope of their insurance arrangements, recovering damages may become considerably more difficult.
The contractor's insurance does not eliminate all potential exposure for the property owner, but it can be an important part of managing the risk.
2. What Is a Certificate of Insurance?
A certificate of insurance is a document that summarizes certain insurance information about a person or business.
A typical commercial insurance certificate may identify:
-
The name of the insured contractor.
-
The insurance company.
-
The insurance broker or agent.
-
The type of insurance carried.
-
The policy number.
-
The liability limit.
-
The policy's effective and expiry dates.
-
Other information requested for the certificate.
For example, a roofing contractor might provide a certificate showing that the business carries $2 million in Commercial General Liability insurance.
This is useful information, but it is important to understand what the certificate actually means.
A certificate of insurance is evidence of the insurance information stated on the document. It is not the insurance policy itself.
A certificate generally does not amend, extend or guarantee coverage.
Any claim remains subject to the actual policy's terms, conditions, limits, exclusions and the circumstances of the loss.
3. Why Isn't a Certificate of Insurance Enough?
A contractor might provide a certificate showing $2 million in liability insurance.
That sounds reassuring.
However, the certificate may not tell you whether the insurance company has agreed to insure the specific work being performed.
For example, a contractor may have arranged insurance for interior painting but subsequently started performing roofing work.
If the contractor did not advise their insurance company of the change in operations, there could be serious questions about how the policy applies to a roofing-related loss.
Similarly, a policy may contain exclusions or limitations that are not apparent from the certificate.
Other potential concerns include:
-
The certificate has expired.
-
The named insured is not the business performing the work.
-
The policy has been cancelled or changed since the certificate was issued.
-
The contractor is performing operations not contemplated by the insurer.
-
A particular activity is excluded.
-
The available liability limit is inadequate for the project.
This is why obtaining a certificate should be part of a broader review rather than the only step taken before hiring a contractor.
4. What Should You Check on a Certificate of Insurance?
When a contractor provides a certificate, take a few minutes to review the information.
The Name of the Insured
Does the business name on the certificate match the contractor you are hiring?
A contractor may operate under a trade name that differs from its legal name, so a difference does not necessarily indicate a problem.
However, it should be explained.
You want to know that the business performing the work is properly identified under the insurance arrangements.
The Insurance Company
Identify the insurer providing the coverage.
The certificate should also identify the insurance broker or agent who issued it.
The Type of Insurance
For many contractors, Commercial General Liability insurance is particularly important.
However, depending on the project, other insurance may also be relevant.
For example, a contractor using specialized equipment may need equipment insurance, while a contractor providing professional design services may require professional liability coverage.
The Liability Limit
Check the amount of liability insurance shown.
Many contractors carry $2 million in Commercial General Liability insurance, but the appropriate amount depends on the nature and size of the project.
A larger commercial construction project may require substantially higher limits.
The Effective and Expiry Dates
Make sure the policy is shown as effective when the work is scheduled to take place.
If the project will continue beyond the policy's expiry date, request updated evidence of insurance when the policy renews.
Remember that a certificate reflects information at the time it was issued. It does not guarantee that the policy will remain unchanged throughout the project.
5. How Can You Verify a Contractor's Insurance?
If you have questions about the certificate, contact the insurance broker or agent identified on the document.
You can ask whether the certificate was genuinely issued and whether the information can be confirmed.
Because of privacy, contractual and authorization considerations, the broker may need the contractor's consent before providing certain details.
For larger or higher-risk projects, consider asking the contractor to authorize their broker to provide confirmation of the relevant coverage.
You may also want to ask whether the insurer has been advised of the type of work being performed.
A broker may be able to confirm information about the insured operations, but any confirmation should be understood within the limits of what the broker is authorized and able to verify.
No certificate or verbal confirmation can guarantee that an insurer will approve every future claim.
6. What Is Commercial General Liability Insurance?
Commercial General Liability insurance, commonly called CGL, is an important coverage for many contractors.
It generally provides protection against certain third-party bodily injury and property damage claims arising from covered business operations.
For example, if a contractor accidentally causes a fire that damages a customer's building, the contractor's CGL policy may respond, depending on the cause of the loss and the policy wording.
CGL insurance may also provide a legal defence for covered claims.
However, CGL insurance is not a warranty or guarantee of the contractor's work.
It does not automatically pay for every construction defect, poor workmanship issue or contractual dispute.
This distinction is particularly important when hiring contractors for renovations or major repairs.
7. Is Faulty Workmanship Covered by Liability Insurance?
One of the most misunderstood aspects of contractor insurance involves faulty workmanship.
Suppose a contractor installs a roof incorrectly.
Several months later, water enters the building and damages ceilings, insulation and interior finishes.
There are potentially two different issues:
The defective roof installation: The cost of correcting the contractor's faulty work may not be covered by the contractor's liability insurance.
The resulting property damage: Depending on the policy wording, exclusions and circumstances, damage to other property caused by the faulty work may be covered.
The distinction is not always straightforward.
Commercial liability policies contain provisions dealing with the insured's work, products, completed operations and other exposures.
Coverage depends on the precise facts and wording.
Property owners should not assume that a contractor's liability insurance will pay to redo work simply because the work was performed improperly.
A written contract, workmanship warranty and appropriate contractor selection remain important.
8. What Is Completed Operations Coverage?
Some losses do not become apparent until after the contractor has finished the job.
For example:
-
A plumbing connection fails weeks after installation.
-
An improperly installed component contributes to a fire months later.
-
A construction defect results in damage after the contractor has left the site.
Commercial General Liability insurance may include products-completed operations coverage for certain bodily injury or property damage claims arising from completed work.
However, this coverage is subject to policy terms and exclusions.
It does not automatically insure the cost of correcting defective workmanship.
When hiring a contractor for significant work, particularly work involving plumbing, electrical systems, roofing or structural components, completed operations exposure is an important consideration.
9. What About Subcontractors?
Many contractors hire subcontractors to complete portions of a project.
For example, a general contractor renovating a home might hire separate trades for:
-
Electrical work.
-
Plumbing.
-
Roofing.
-
Heating and air conditioning.
-
Flooring.
-
Structural work.
You should understand who will actually perform the work.
A general contractor's insurance does not necessarily mean that every subcontractor has its own appropriate insurance.
The contractor's policy may also contain conditions or limitations relating to subcontracted operations.
Ask whether subcontractors will be used and how their insurance is being addressed.
For significant projects, it may be appropriate to request evidence of insurance from the subcontractors as well.
Your contract should also clearly identify responsibilities for the work being performed.
10. What Is a WSIB Clearance Certificate?
In Ontario, another important consideration is workplace insurance through the Workplace Safety and Insurance Board (WSIB).
A WSIB clearance confirms the relevant business's status with WSIB for the applicable period.
It is different from a certificate of Commercial General Liability insurance.
A contractor could have liability insurance but still have separate WSIB obligations.
Similarly, WSIB coverage is not a replacement for commercial liability insurance.
WSIB registration and coverage requirements depend on the business, industry and circumstances. Special rules apply to much of the construction industry, subject to certain exemptions.
For construction work, principals may have specific responsibilities concerning contractor clearance certificates.
Property owners and businesses should check the applicable WSIB requirements rather than assuming that every project is treated identically.
You can find information about clearances through the Workplace Safety and Insurance Board at www.wsib.ca.
11. Should You Ask to Be Added as an Additional Insured?
For some projects, a contract may require the property owner, landlord or another party to be added as an additional insured under the contractor's liability policy.
An additional insured endorsement may provide specified liability protection to another party for certain claims connected with the named insured contractor's operations.
However, the protection depends on the wording of the endorsement.
Being named as an additional insured does not mean that you receive all the coverage available to the contractor.
It also does not automatically insure your building against every type of damage.
An additional insured requirement is more common in commercial contracts and larger construction projects, but it may be relevant in other situations.
If a contract requires additional insured status, the requirement should be reviewed with the appropriate insurance professionals before work begins.
12. Does Your Own Property Insurance Cover Damage Caused by a Contractor?
Possibly, depending on the circumstances.
For example, if a contractor accidentally causes a fire, your property insurance may respond to insured damage to your building, subject to the policy wording.
However, that does not mean every loss connected with renovations is automatically covered.
Insurance companies may have specific requirements or restrictions relating to:
-
Major renovations.
-
Structural alterations.
-
Roof replacement.
-
Buildings under construction.
-
Properties that are temporarily vacant or unoccupied.
-
Changes to plumbing, electrical or heating systems.
-
Projects involving substantial increases in property value.
Some renovation projects may require policy changes, additional coverage or a specialized course of construction policy.
Before beginning a significant renovation, notify your insurance broker.
Your insurer should have an opportunity to review the work and determine whether any changes to the insurance arrangements are necessary.
13. What About Damage to the Work Under Construction?
A contractor's liability insurance and a property owner's existing insurance may not fully address damage to a construction project itself.
For example, materials awaiting installation or partially completed construction work may require specialized coverage.
Depending on the project, a builder's risk or course of construction policy may be appropriate.
This type of insurance can provide coverage for specified physical loss or damage to insured construction property during the project.
Coverage, exclusions and responsibility for arranging the policy vary.
For larger renovations or construction projects, the owner and contractor should determine in advance who is responsible for obtaining this coverage.
14. Why a Written Contract Is Important
Insurance is only one part of managing the risks of hiring a contractor.
A written contract helps establish the responsibilities and expectations of everyone involved.
Depending on the project, the contract should address:
-
A clear description of the work.
-
Materials and specifications.
-
Project cost and payment schedule.
-
Start and anticipated completion dates.
-
Permits and inspections.
-
Responsibility for subcontractors.
-
Insurance requirements.
-
Procedures for changes to the work.
-
Warranties and deficiencies.
-
Dispute resolution.
For major projects, consider obtaining legal advice before signing.
Be particularly careful about contractual clauses that attempt to transfer significant liability to you or require you to waive rights.
Insurance does not necessarily cover every obligation accepted under a contract.
15. Other Steps to Take Before Hiring a Contractor
In addition to reviewing insurance, consider the contractor's qualifications and business practices.
Check References
Ask for references from previous customers who had similar work completed.
Where practical, follow up with those customers.
Confirm Qualifications
Depending on the work, the contractor or tradesperson may need specific licences, certifications or other qualifications.
For example, certain electrical work in Ontario must be performed by an appropriately licensed electrical contractor, subject to applicable exceptions.
Ask About Permits
Find out whether building permits or inspections are required and who will be responsible for obtaining them.
Obtain a Detailed Estimate
Make sure the quotation clearly describes the proposed work, materials and pricing.
Avoid Large Unexplained Upfront Payments
Understand the payment schedule and be cautious about paying substantial amounts before work has been completed.
Be Wary of High-Pressure Sales Tactics
Take time to review quotations, contracts and credentials before making a decision.
A contractor who refuses to provide reasonable documentation or pressures you to proceed immediately may warrant additional scrutiny.
16. What if the Contractor Says They Don't Need Insurance?
Some contractors may suggest that insurance is unnecessary because the project is small or they have never had a claim.
Others may offer a lower price if the work is performed without formal documentation.
This should be approached cautiously.
A relatively small project can still result in significant damage.
For example, a minor plumbing repair could cause extensive water damage if something goes wrong.
A contractor's confidence in their workmanship is not a substitute for appropriate insurance.
If a contractor cannot provide reasonable evidence of insurance or explain their insurance arrangements, consider whether you are comfortable accepting the potential risk.
17. A Practical Checklist Before Work Begins
Before hiring a contractor, consider the following:
-
Confirm the contractor's legal business name and contact information.
-
Review references and qualifications.
-
Obtain a detailed written quotation and contract.
-
Request a current certificate of liability insurance.
-
Check the named insured, limits and policy dates.
-
Ask whether the coverage reflects the work being performed.
-
Confirm whether subcontractors will be involved.
-
Review applicable WSIB clearance requirements.
-
Determine whether additional insured coverage is needed.
-
Notify your own insurance broker about significant renovations.
-
Confirm who is responsible for insuring materials and work under construction.
Not every step will apply in the same way to every project.
The more complex or hazardous the work, the more important a thorough review becomes.
Protecting Your Property Starts Before the Work Begins
Hiring a contractor involves placing considerable trust in another business.
You expect the contractor to perform the work properly, but you should also consider what happens if an accident, injury or property damage occurs.
A certificate of insurance is an important document to request, but it should not be treated as a guarantee of coverage.
Taking time to verify the contractor's qualifications, understand the insurance arrangements and review the contract can help reduce the risk of unpleasant surprises.
At L.D. Dermody Insurance Brokers, we encourage our clients to contact us before undertaking significant renovations or construction projects.
We can help review how the proposed work may affect their existing insurance and discuss whether additional coverage should be considered.
If you are planning a renovation or have questions about insurance when hiring a contractor, contact L.D. Dermody Insurance Brokers. We would be pleased to help you understand your insurance considerations before the work begins.
This article provides general information for Ontario property owners and businesses as of October 2026. Insurance coverage depends on the actual policy wording, endorsements, exclusions and circumstances of a loss. WSIB, licensing, contractual and construction requirements should be verified with the appropriate authorities and professional advisers.

